The GENIUS Act’s reserve rules are scheduled to take effect on January 18, 2027. In a research note reported by Odaily on November 10, 2026, the Bank Policy Institute (BPI) assessed how the ten largest dollar stablecoins’ reserves compared with those rules. BPI’s conclusion was about reserve composition, not a guarantee that any token will maintain its peg.
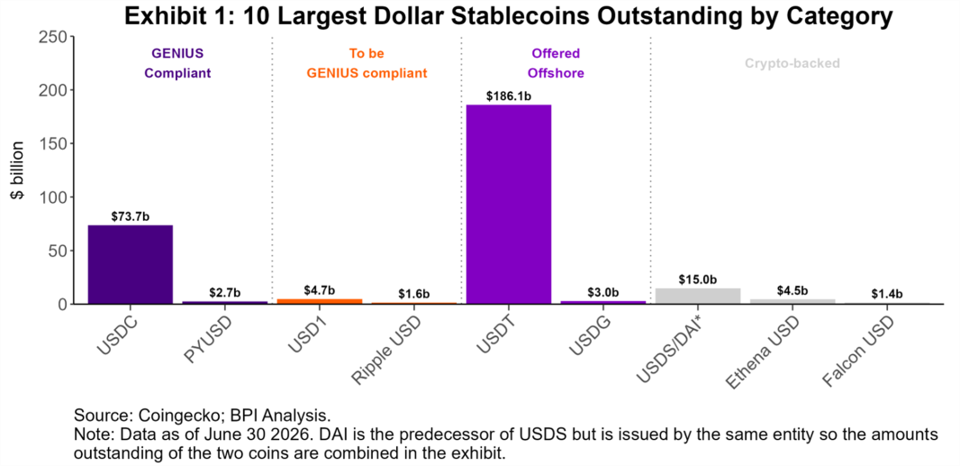
BPI reported that two tokens—USDC and PYUSD—held reserves consistent with the requirements, representing 26% of total dollar-stablecoin circulation. Two more represented 2% and were expected to meet them. The remaining 72% comprised offshore-issued stablecoins (65%) and crypto-backed stablecoins (7%) whose reserves did not match the requirements. The ten-token sample represented 97% of market circulation as of June 30, 2026.
Method and scope
BPI, whose authors were Laurence Bristow and Eva Funaki, used issuer disclosures for reserve composition; USDT disclosed quarterly rather than monthly. It used Dune Analytics on-chain data for the crypto-backed USDS and DAI. The figures were generally measured as of June 30, 2026, although the article’s USDC reserve breakdown refers to July 2026. BPI represents the US banking industry, a relevant perspective when weighing its conclusions about offshore and crypto-backed issuers.
Under the Act, payment stablecoins issued in the United States or offered to US users must be fully backed by eligible liquid assets, including US Treasury securities with no more than 93 days remaining to maturity, overnight Treasury-backed reverse repurchase agreements and bank deposits. The Act also provides a route for foreign issuers to serve US users if the US Treasury finds their home-country regime comparable and they demonstrate an ability to comply with US legal orders.
Where the reserve structures differ
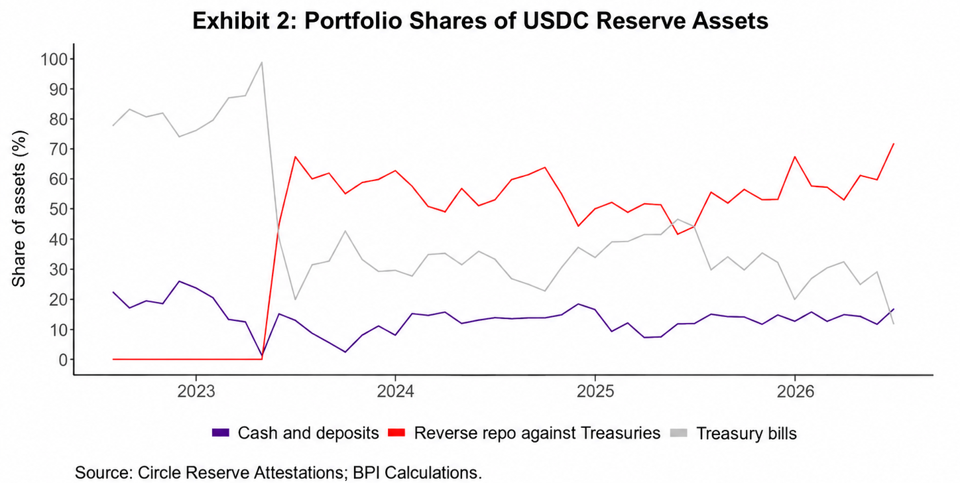
Of the four tokens in the sample issued in the United States, BPI found that Circle’s USDC and Paxos’s PYUSD met the reserve-asset requirements as of June 2026. World Liberty’s USD1 and Ripple USD did not: both held money-market funds containing agency debt and longer-maturity Treasuries. In July 2026, roughly 70% of USDC’s reserves were Treasury-backed reverse repos; the remaining 30% was split approximately evenly between uninsured bank deposits and Treasury bills.
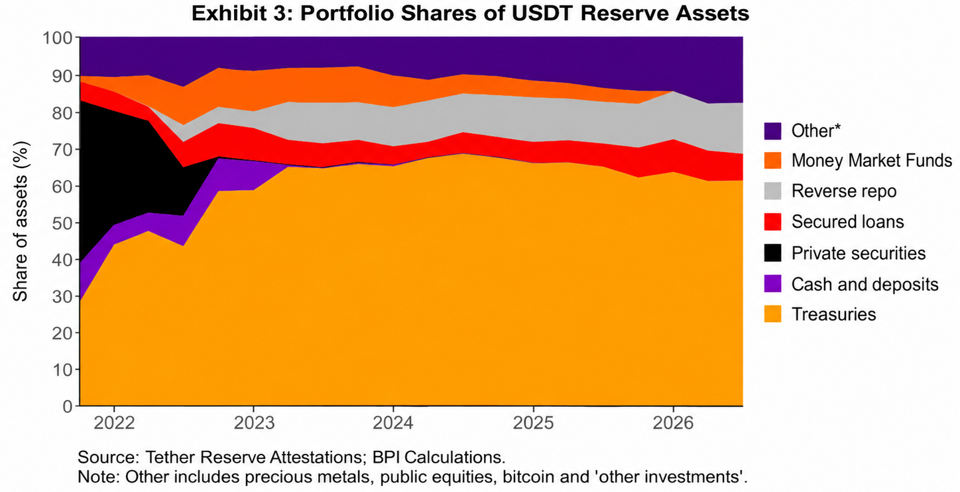
The largest offshore-issued token, USDT, held 61% of its reserves in Treasury bills and 10% in overnight Treasury-backed reverse repos as of June 30, 2026, according to the article. Bank deposits were a small share. Gold, listed equities, bitcoin, secured loans, term repo loans and other investments made up the remaining 29%. USDG, issued by Paxos entities in Singapore and Europe, held 53% in government money-market funds, 42% in Treasury bills and 5% in bank deposits. BPI’s objection to the funds was that they can hold Treasury securities beyond the Act’s 93-day limit and federal agency securities.
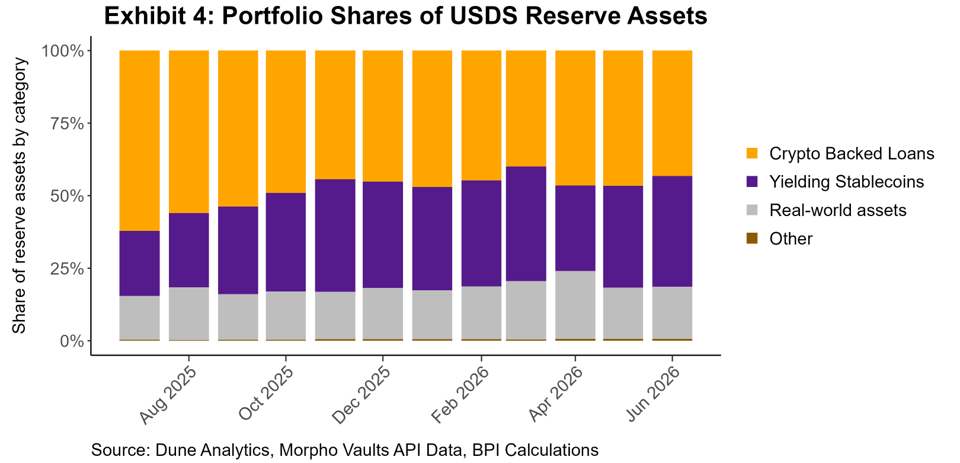
For crypto-backed tokens, the difference is more fundamental: crypto-collateralized loans are not eligible reserve assets under the payment-stablecoin rules. Sky Protocol’s USDS can be minted by exchanging USDC, borrowing against crypto collateral through Sky’s DeFi lending protocol, or through credit extended to affiliated entities for strategies including crypto-backed loans and tokenized real-world assets. In June 2026, its reported reserve mix was 42% crypto-backed loans, 38% stablecoins and 20% tokenized real-world assets. Ethena Labs’ USDe, at approximately $4 billion that month, was backed by a mix of tokenized real-world assets, yield-bearing stablecoins and crypto-backed loans on DeFi protocols, following a change from its original basis-trading strategy.
What compliance can—and cannot—show
BPI’s comparison identifies a substantial gap between the Act’s eligible-reserve standard and the assets backing much of the stablecoin market in its June 2026 snapshot. It does not establish that compliant reserves eliminate depegging risk: the article notes that both compliant and non-compliant stablecoins have previously traded below their pegs. Reserve eligibility is one measure of risk, not a complete test of stability.
Source: odaily.news (originally published 2026-11-10 15:03 UTC+8)