Historical report: Published November 9, 2026, at 16:05 Beijing time. The figures and plans below reflect the original reporting period, not current conditions.
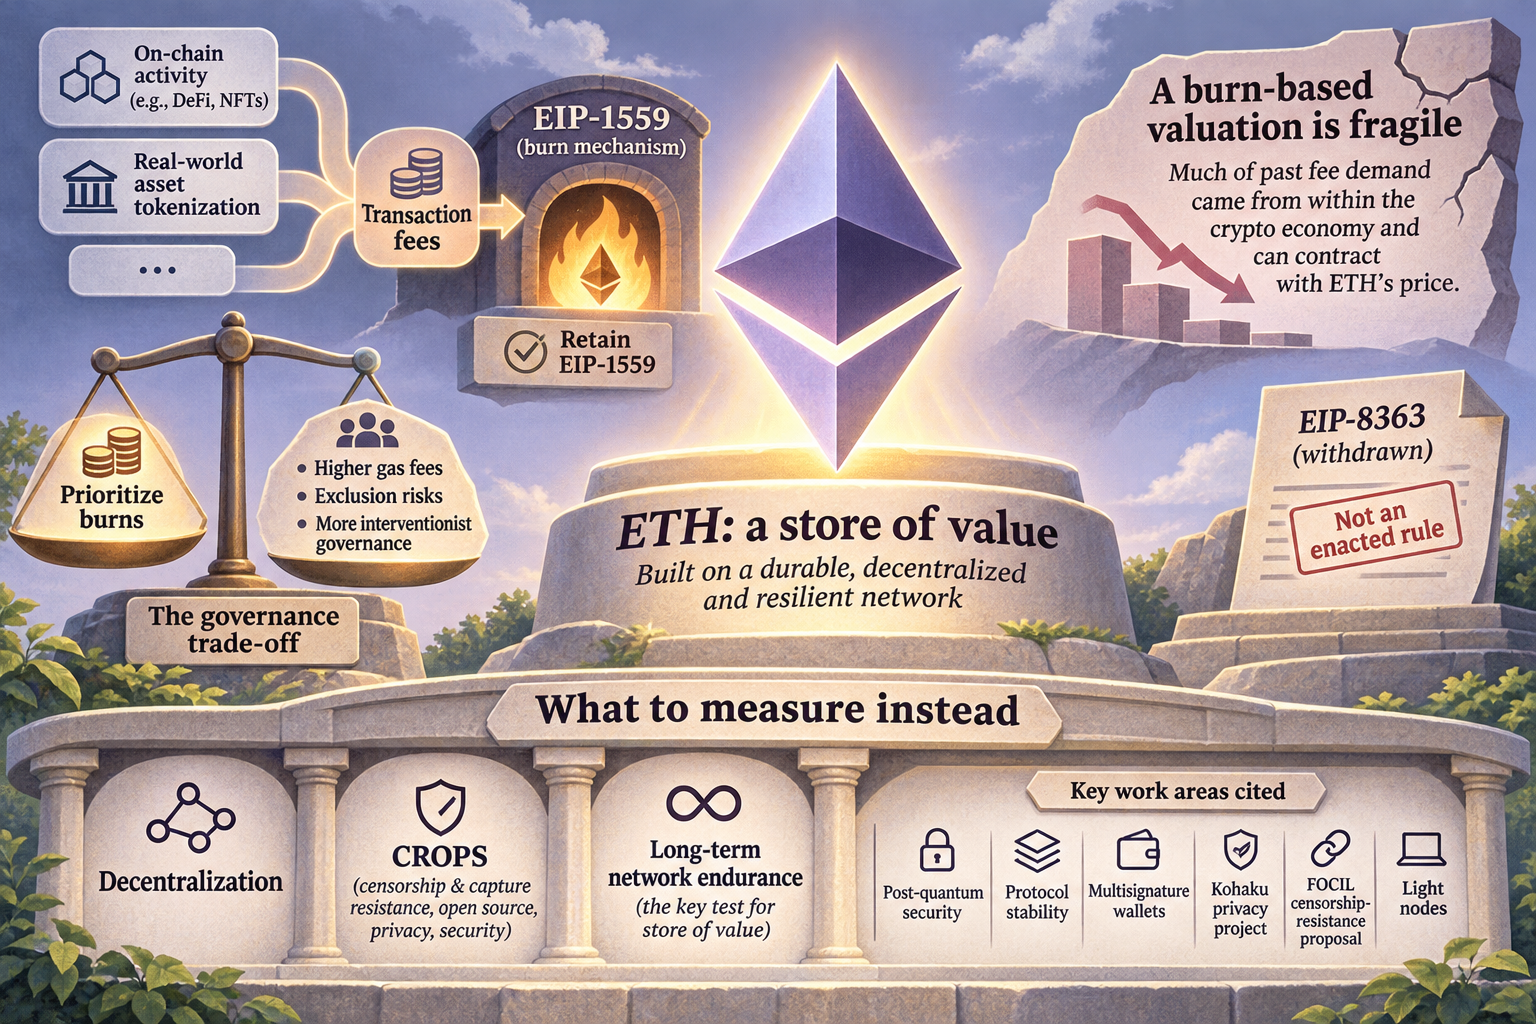
Vitalik Buterin argued in an X post on November 8 that ETH is better understood as a store of value than as a token valued primarily through transaction-fee burns. He supported retaining EIP-1559, introduced in 2021, and said its burn mechanism works well even if it offsets only part of new ETH issuance. His objection was to treating the burn as the foundation of ETH’s valuation.
Why a burn-based valuation is fragile
Buterin described a model that divides the annual value of burned tokens by a discount rate. At $1 billion burned per year and a 4% rate, it produces a theoretical $25 billion valuation floor. He argued that the floor is not dependable: much of the demand behind burns in 2021–2023 came from within the crypto economy and could contract alongside ETH’s price. He said the logic would hold only if the fee-generating demand came from the outside world.
As an example of a short-lived fee surge, Buterin cited the Otherside land sale by Yuga Labs, during which a single day’s burns reached $180 million. He said growing real-world asset tokenization gives Ethereum a better basis for external demand, but that such activity is unlikely to reproduce earlier fee spikes.
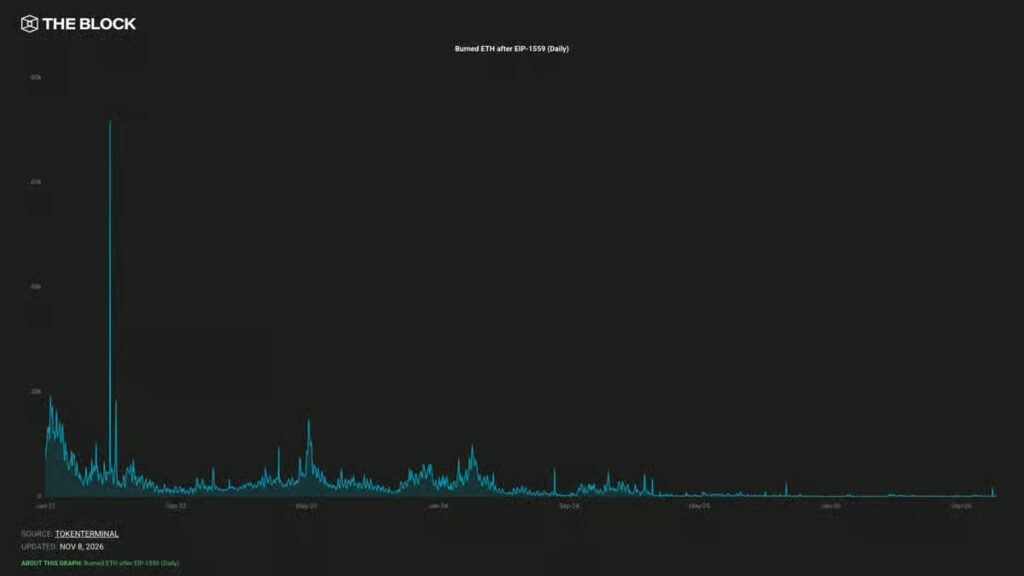
The Block’s burn data, as reported in the original article, illustrates the change in scale: approximately 1.48 million ETH, worth about $3.6 billion, was burned in 2022, versus approximately 19,200 ETH, worth $43 million, in 2026 through the article’s reporting date. Those totals describe different measurement periods; they are not annualized comparisons.
The governance trade-off
Buterin also questioned what it would take to support a roughly $270 billion ETH market capitalization through burns alone. The Block put ETH’s market capitalization at $273.3 billion on the Sunday morning covered by the report. Using an AI-generated estimate that L’Oréal spends about 0.58% of its market capitalization on research and development, Buterin argued that an Ethereum operation funded at a comparable rate would rapidly exhaust the Ethereum Foundation’s funds. In his comparison, protocol funding of about 700,000 ETH annually would instead cut validator income by two-thirds. This was an analogy and estimate, not a proposed Ethereum budget.
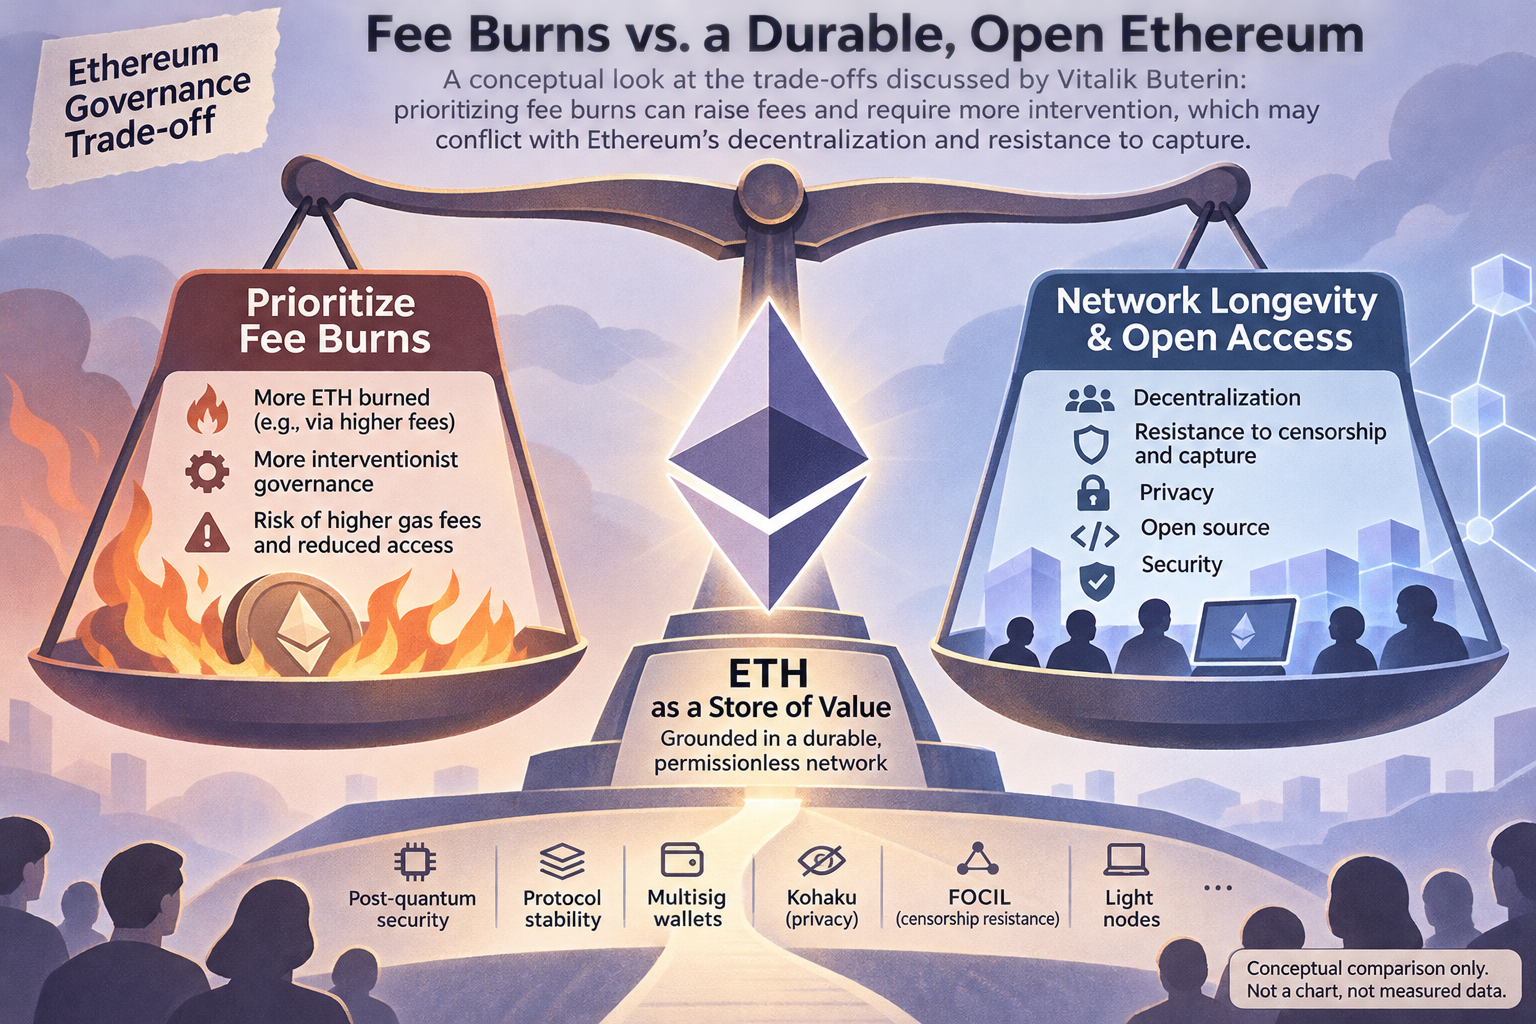
More fundamentally, he argued that optimizing the network for burns would require more interventionist governance. Prioritizing burns could also mean higher gas fees, potentially excluding users who most need privacy and security. In his account, those outcomes conflict with Ethereum’s decentralization and resistance to capture.
What he would measure instead
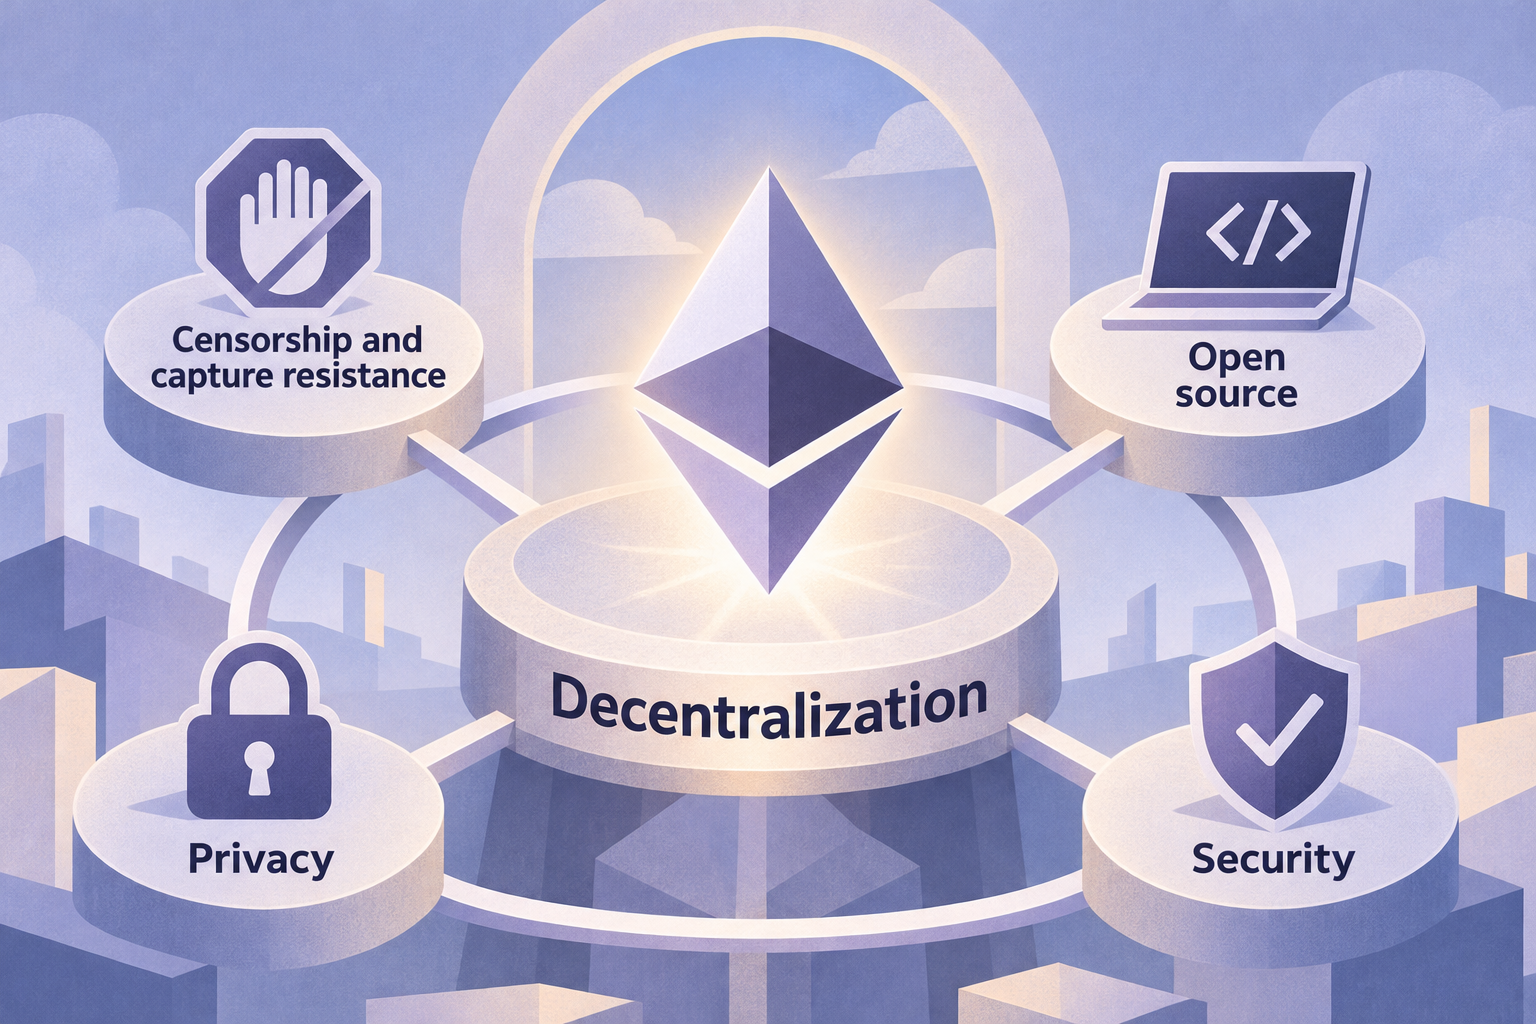
Buterin pointed to decentralization and what he called CROPS: resistance to censorship and capture, open source, privacy, and security. For ETH’s store-of-value case, he identified the network’s ability to endure as the foremost test. He connected that goal to work on post-quantum security, protocol stability, multisignature wallets, the Kohaku privacy project, the FOCIL censorship-resistance proposal, and light nodes. These are priorities he cited, not evidence that each has been completed.
The governance debate remained open. Five weeks before Buterin’s post, the co-authors of EIP-8363 withdrew the proposal from consideration for the planned Hegota upgrade. It would have increased the share of validator rewards burned as ETH staking grew; it was not an enacted rule. The original report also noted opposition from SharpLink CEO Joseph Chalom and Aave founder Stani Kulechov.
Buterin’s argument leaves EIP-1559 intact while narrowing what its burn data can establish: fee destruction records network activity, but a durable valuation case depends on the source of that demand and on whether the network retains the properties its users value.
Source: panewslab.com (originally published 2026-11-09 16:05 UTC+8)